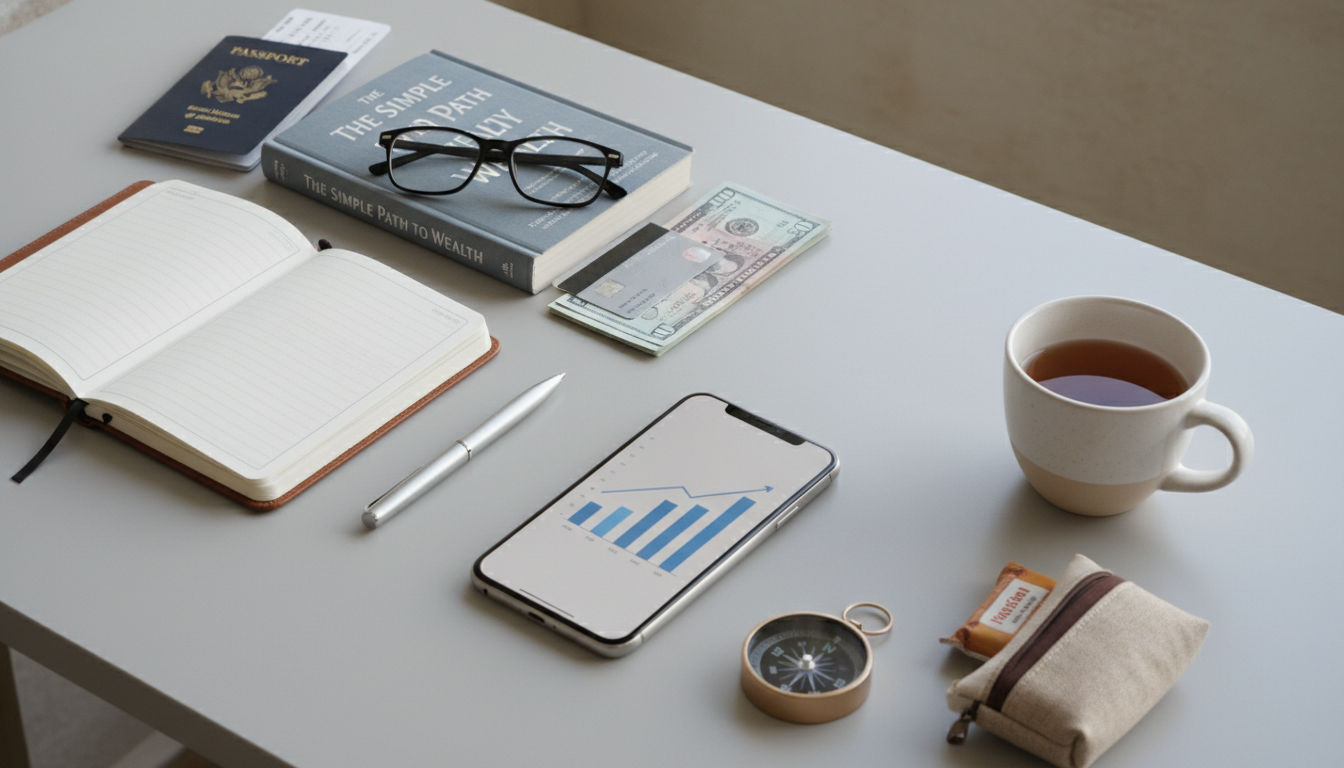
The Simple Path to Wealth boils personal finance down to a few repeatable moves: spend less than you earn, invest the gap automatically, and keep investing simple enough that you’ll actually stick with it for decades. The core message is that wealth is built more by behavior and time than by clever stock picking.
The book puts heavy emphasis on living below your means and avoiding lifestyle inflation. A higher savings rate does two jobs at once: it grows the money you can invest and reduces the amount you need to retire. The “simple path” starts with making room in your budget so investing becomes inevitable, not optional.
Instead of chasing hot sectors or paying high fees, the strategy centers on diversified index funds—especially total stock market exposure—because costs, taxes, and complexity quietly erode returns. Simplicity is treated as an advantage: fewer moving parts means fewer mistakes when markets get noisy.
High-interest consumer debt is framed as a direct barrier to financial independence. If debt must be used, the message is to keep it limited, intentional, and compatible with long-term investing—rather than allowing monthly payments to crowd out contributions.
A major point is psychological: volatility is normal, and selling in a panic is one of the most expensive errors investors make. The approach encourages setting an allocation you can live with, continuing to buy through downturns, and letting compounding do the heavy lifting.
The end goal is “FU money”—enough invested assets to cover your spending so work becomes a choice. That’s the bridge to a slower, more flexible life where you can prioritize time, health, and relationships. For a practical breakdown that connects minimalist living with passive-income thinking, see the full guide here: https://splendona.com/guide-simple-wealth-slow-living-minimalist-passive-income/.
Aim for a savings rate that feels challenging but sustainable—many people target 15–30% as a starting range, then increase over time. The best number is the one you can maintain through good markets and bad.

Leave a comment